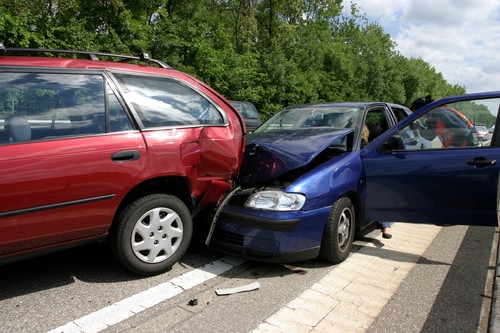
Insurance coverage for Door Dash accidents can be more complex than you may realize. In fact, if you’re a Door Dash driver, some combination of your personal auto insurance and Door Dash insurance can cover you on the roads at different points – but each comes with specific limits, and both do not necessarily cover …
Insurance coverage for Door Dash accidents can be more complex than you may realize. In fact, if you’re a Door Dash driver, some combination of your personal auto insurance and Door Dash insurance can cover you on the roads at different points – but each comes with specific limits, and both do not necessarily cover any accident you’re in.
To help you understand how Door Dash insurance works and when it applies (and when it doesn’t), here is a simple guide to Door Dash accidents, Door Dash insurance coverage, and what to do after a Door Dash accident.
Door Dash Accidents Resources
The more you know about Door Dash accidents and insurance, the better equipped you’ll be to protect your rights if you’re ever hurt in one of these crashes. To start getting more answers and info about these wrecks, click on a question below and jump directly to the answer.
Door Dash drivers are required to have their own auto insurance in order to secure employment with the company. This coverage must meet the state requirements for minimum liability limits. Here’s more on the Texas auto insurance requirements that Door Dash drivers and other motorists must comply with.
Once employed by Door Dash – and with their own auto insurance coverage active – drivers will also have coverage from the company’s “occupational accident policy.”
With this Door Dash occupational accident policy:
Drivers do have to pay fees to activate the coverage. It’s automatically activated upon getting hired to drive for the company.
It covers Caviar couriers who are making deliveries (as of December 1, 2019).
Door Dash drivers making deliveries are also covered (as of June 27, 2019).
The driver’s own auto insurance is considered the primary coverage, and the Door Dash coverage is a secondary policy, kicking in only after the primary coverage has been applied and exhausted.
Property damage to Door Dash drivers’ vehicles is NOT covered.
Along with this Door Dash insurance, the company also has commercial coverage of up to $1, 000, 000 in bodily injury and/or property damage. This coverage applies:
During active deliveries, meaning drivers are en route to pick up an order or deliver it to a customer
To third parties hurt in accidents caused by delivery drivers but only after the primary insurance has been exhausted
How Does Driving for Door Dash Affect Car Insurance?
Since Door Dash motorists earn money for activities involving driving, insurance companies can consider that time on the roads to be commercial driving activity. That’s not the same as personal driving, and it means that:
Personal auto insurance does not necessarily cover commercial driving activity.
Door Dash drivers likely need a commercial policy or special add-ons to supplement a personal auto insurance policy.
Motorists should inform their insurers about their gigs for Door Dash.
Door Dash drivers who don’t obtain the necessary extra coverage may find themselves without insurance coverage for some accidents.
What Coverage Applies to Crashes Caused by Door Dash Drivers?
Coverage for car accidents caused by Door Dash drivers depends on the circumstances of the wreck. Specifically, the Door Dash driver’s “status” at the time of the collision typically determines which insurance policy applies and:
If the Door Dash driver WAS NOT making a delivery when the crash happened, Door Dash coverage does NOT apply. The at-fault driver’s auto insurance coverage will come into play, instead, meaning the Door Dash driver’s own personal or commercial policy. If this coverage is insufficient, victims may have other options for pursuing recovery, like filing an uninsured/underinsured motorist (UM/UIM) claim with their own insurance provider.
If the Door Dash driver WAS making a delivery at the time of the collision, the Door Dash coverage would typically come into play. Notably, however, the driver’s own insurance would need to be exhausted first, before the Door Dash occupational and commercial coverage is applied.
If Door Dash drivers and other motorists share liability, others’ coverage would be primary, with the Door Dash coverage being secondary. Again, the at-fault drivers’ personal insurance would come into play first, before the Door Dash policy provides any coverage.
Remember, just because insurance coverage should apply to give a car crash does NOT necessarily mean that insurers will stand by their policies or agree that they should cover that wreck. In fact, it’s not uncommon for auto wreck victims to have to push back on insurance companies that wrongfully deny coverage.
What Does Door Dash Insurance Cover?
The Door Dash occupational accident coverage provides up to:
$1, 000, 000 for medical expenses, with no deductible or co-pay
$500 a week in disability payments
$150, 000 in survivors’ payments, for eligible dependents
The Door Dash commercial coverage provides up to $1, 000, 000 in bodily injury and/or property damage.
What Should I Do After a Door Dash Car Accident?
After a Door Dash crash, take as many of these steps as possible. Doing so can protect your rights and interests, regardless of whether you drive for Door Dash or not. And if you’re not able to do much after a collision, skip to the last step:
Quickly move to a safe place.
Call police. Dial 911 if anyone has been hurt or if the crash happened in a high-traffic area.
Wait at the scene until the police arrive and give you the OK to go.
Seek medical attention ASAP, either letting EMTs treat you at the scene, going to a nearby ER, or seeing a physician as soon as you can after the wreck.
Exchange names, contact info, and driving/insurance info with others involved in the crash. Snap pictures of driver’s licenses, insurance cards, and license plates to simplify this.
Take pictures and videos of the accident scene, the damage, the roads, and the weather conditions. Also, try to take pictures of other parties involved in the crash and what’s generally happening at the crash scene during the initial investigations after the collision.
Report the accident to your insurance company as soon as reasonably possible after the collision.
If you will be filing a claim under the Door Dash policy, you will also need to complete the Door Dash Accident Report Form.
Continue getting the medical care needed and prescribed for your crash injuries.
Consult a Door Dash car accident lawyer to get more information about your rights and legal options.
How Do I File a Door Dash Accident Claim?
Filing a Door Dash crash claim can start with accident investigations and reporting the collision to insurance companies. With that, however, it’s crucial to know that:
Insurance companies are not focused on protecting your rights: Insurers involved in Door Dash crash claims are usually looking for ways to dodge liability and avoid making payouts. After all, they profit when they don’t make payouts. So, even if you are legally entitled to compensation, don’t count on insurers to offer you what you may deserve. Instead, assume that you will need to push back and that insurers will be out to lowball you. If you do, you’ll be better prepared to safeguard your rights and interests whenever you have to interact with insurance companies.
Insurers are skilled at minimizing payouts: There are all sorts of tactics insurance companies use to reduce and avoid making payouts. They may try to use your words against you, misinterpret the evidence, prolong claims investigations, or undercut the severity of your injuries. Sometimes, they may even try to (illegally) rewrite policies after the crash in an effort to say that a collision wasn’t covered. Sadly, these tactics can work, resulting in some crash victims being victimized again during the claims process.
An experienced lawyer can protect your rights and claim: An attorney can identify fault, assert your rights, and stand up to insurance companies throughout the Door Dash accident claims process.
Compensation from Door Dash accident claims can help victims cover medical expenses as they pick up the pieces and focus on healing.
To set claims up for success and full, fair compensation, it’s prudent to talking to an attorney.
Share This Post
Author
James Amaro
Founder and Attorney
James Amaro founded the Amaro Law Firm in 2005 to help people and businesses facing life-changing losses hold negligent parties accountable. Over the last 20 years, James Amaro has earned an outstanding reputation nationwide as a highly skilled attorney and a tenacious trial lawyer in personal injury cases, business disputes, insurance claims, hurricane claims, and commercial litigation.
Chris Gadoury joined the Amaro Law Firm in 2023 and brings over two decades of nationwide experience in litigating complex commercial, environmental, False Claims Act, and white-collar criminal litigation to represent the Firm’s clients in wrongful death, catastrophic personal injury, commercial, and environmental matters. Prior to the Amaro Law Firm, Mr. Gadoury litigated for a combined 17 years as a Partner with Berg & Androphy and as Senior Counsel at the Lanier Law Firm. His vast experience of representation spans that of Fortune 100 companies, small businesses, individuals and families, and hedge funds and institutional investors with billions in assets.
 Coverage for car accidents caused by Door Dash drivers depends on the circumstances of the wreck. Specifically, the Door Dash driver’s “status” at the time of the collision typically determines which insurance policy applies and: