Diminished Value Claims in Texas: Why Insurers Deny Them and What Steps You Can Take
Texas allows an injured third party to pursue diminished value when a vehicle is worth less after an accident and repairs, but proving the amount of that loss can be difficult. Insurance companies often deny or minimize these claims because diminished value is harder to establish than repair costs, and insurers may dispute whether the vehicle actually lost market value or how much it lost.
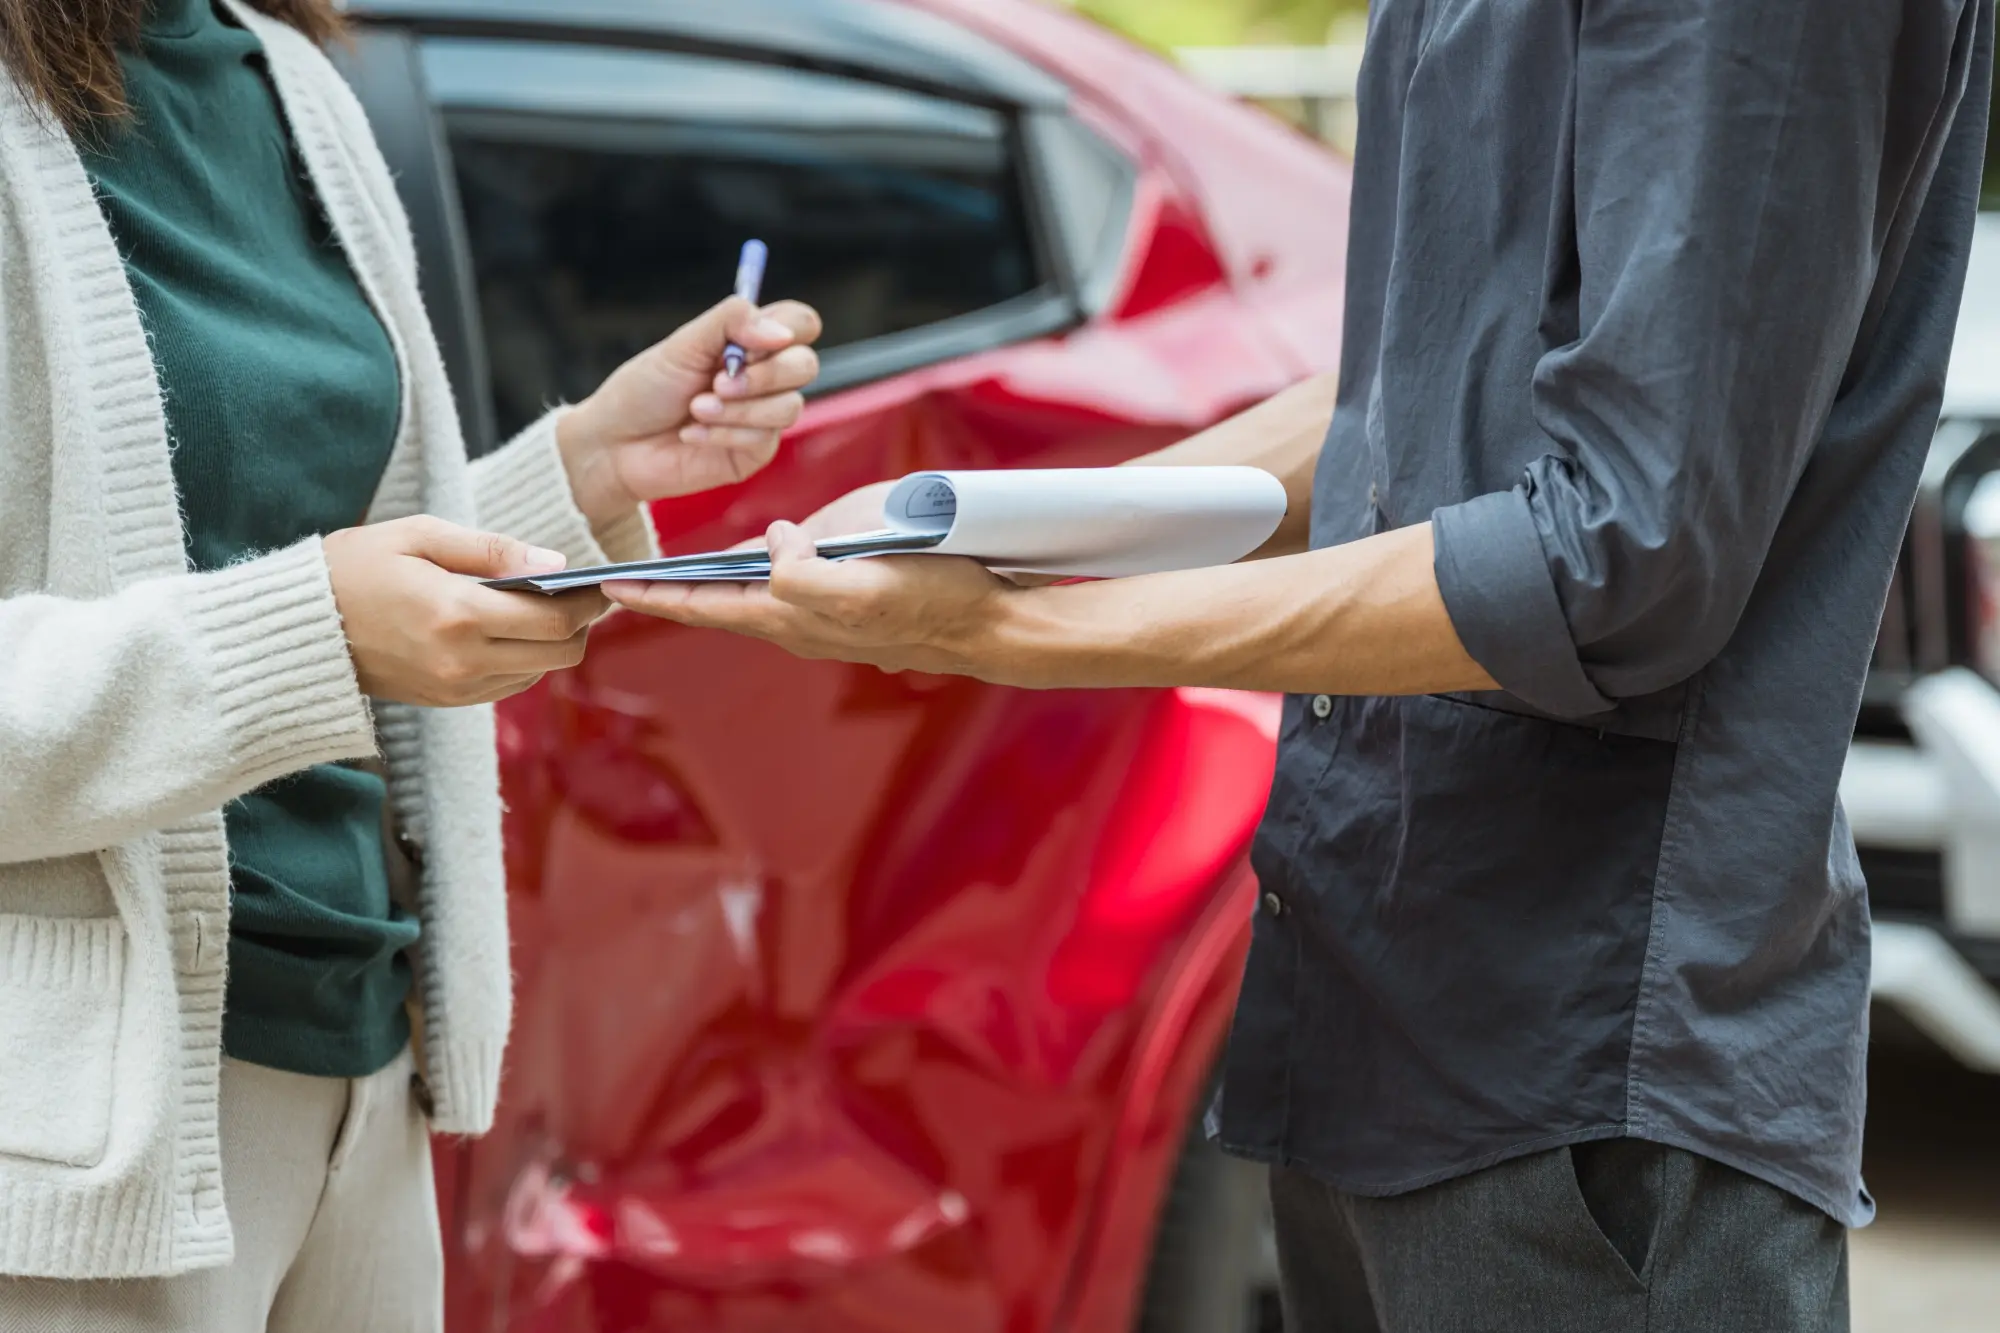
A diminished value claim seeks compensation for the difference between what your vehicle was worth before an accident and what it is worth after being repaired. Even if repairs restore the vehicle’s appearance and function, an accident history can make the vehicle less valuable to a future buyer.
For example, a vehicle that has been involved in a significant collision may be worth less than an otherwise identical vehicle with a clean accident history. Buyers may be concerned about previous damage, repairs, structural issues, or the possibility of future problems.
If an insurer has denied your diminished value claim, you may be left feeling like you have no options to recoup your losses, but that is not necessarily true. The evidence supporting the vehicle’s lost market value — and whether the claim is being made against the at-fault driver’s insurer or your own policy — can make a significant difference.
Yes, but the answer depends on whose insurance policy you are claiming against. Texas draws an important distinction between first-party claims under your own policy and third-party claims against the at-fault driver’s insurance.
The Texas Department of Insurance has stated that an insurer generally is not required to pay diminished value under a standard first-party physical-damage policy when the vehicle has been completely repaired to its pre-damage condition. However, TDI also states that a third-party claimant may have a claim for loss of market value regardless of how completely the vehicle was repaired.
In other words, if another driver’s negligence caused the accident, your potential diminished value claim against that driver’s liability insurer is different from a claim under your own collision coverage.
How Is Diminished Value Calculated in Texas?
One common approach to determining diminished value is the 17c formula. While Texas does not require the 17c formula as the legal method for calculating diminished value, it can be useful as a starting point for negotiations. The commonly used 17c calculation is:
Determine the vehicle’s pre-accident value.
Calculate 10% of that value as the base loss.
Apply a damage severity modifier based on the extent of the damage.
Apply a mileage modifier based on the vehicle’s mileage.
The resulting figure is the estimated diminished value.
For example, a $30,000 vehicle would have a $3,000 base loss under the formula. That amount would then be reduced by the applicable damage and mileage modifiers.
The important point is that 17c is a negotiating tool, not a Texas statute or mandatory valuation method. It can give you a baseline for understanding an insurer’s offer, but you can support a different valuation with evidence showing what your particular vehicle actually lost in market value.
Are Diminished Value Claims Usually Accepted?
Not always. Insurance companies frequently challenge diminished value claims, particularly when the claimant cannot provide evidence that the vehicle actually lost market value or cannot establish how much value was lost.
A diminished value claim is different from submitting a repair bill. The cost of repairing physical damage can generally be documented through estimates and invoices. Diminished value requires evidence of what the vehicle would have been worth without the accident compared with what it is worth after the accident.
Texas courts have emphasized that a claimed loss in value needs factual support rather than simply an unsupported assertion about the vehicle’s market value. Evidence can include comparable sales, appraisals, valuation information, and other relevant market evidence.
What Are the Common Reasons for Rejecting a Diminished Value Claim?
An insurer may deny or reduce a diminished value claim for several reasons, including:
The insurer disputes liability. If the insurer does not believe its driver was responsible for the accident, it may refuse to pay the claim altogether.
The insurer says the vehicle was fully repaired. Complete repairs do not necessarily eliminate third-party diminished value, but an insurer may still argue that the repairs restored the vehicle’s value.
There is not enough evidence of actual market loss. A claimant generally needs more than a statement that the vehicle is worth less because it was in an accident.
The vehicle already had an accident or damage history. Previous damage can make it harder to establish that the current accident caused an additional loss in value.
The vehicle has high mileage or substantial prior depreciation. The insurer may argue that the accident had little additional effect on its market value.
The insurer relies on a 17c calculation. A carrier may use the formula to produce a relatively low valuation and argue that the resulting amount is all that is owed.
The claim is being made under the wrong coverage. First-party and third-party diminished value claims can be treated differently under Texas insurance policies.
Why Some Injury Firms Won’t Take on a Denied Diminished Value Claim
Some personal injury firms do not take diminished-value-only cases because the potential recovery may be too small to justify the time and expense required to litigate the dispute. If there is no significant bodily injury claim or other substantial damages, an attorney may not be able to handle the case economically while being paid on a contingency-fee basis.
This can be frustrating for someone who knows their vehicle is worth less after an accident. It does not necessarily mean your claim is invalid, but simply means that pursuing the claim through traditional litigation is not cost-effective.
How Can You Get the Most out of a Diminished Value Claim, and when a Lawyer May Be Needed
If you are handling a diminished value claim yourself, focus on proving the vehicle’s actual market loss rather than relying exclusively on an insurer’s formula. If your diminished value claim is part of a larger personal injury or property-damage dispute, involving an attorney may make more sense.
Start by gathering documentation that establishes:
Your vehicle’s pre-accident value
The extent of the accident damage
The vehicle’s post-accident history
Comparable vehicles of similar make, age, mileage, etc.
A professional valuation, when appropriate
The insurer’s calculation
If the insurer offers a 17c-based amount, you do not necessarily have to accept it simply because the adjuster calls it the diminished value of your vehicle. You can use that figure as a starting point for negotiations and then present evidence supporting a different amount.
If you also suffered serious injuries in the crash, however, the situation changes considerably. Your diminished value claim may be only one component of a much larger personal injury claim involving medical expenses, lost income, pain and suffering, and other damages. That is when consulting a personal injury attorney may be particularly worthwhile.
Insurance Company Not Playing Fair? Contact Amaro Law Firm.
If an insurance company has denied your claim, offered an amount you believe is unfair, or refused to recognize the value your vehicle lost after an accident, you do not have to navigate the insurance process alone.
Amaro Law Firm can review the circumstances of your accident and help you understand what options may be available. If you suffered injuries in the crash in addition to damage to your vehicle, speaking with an attorney can be especially important because your potential claim may extend well beyond diminished vehicle value.
James Amaro founded the Amaro Law Firm in 2005 to help people and businesses facing life-changing losses hold negligent parties accountable. Over the last 20 years, James Amaro has earned an outstanding reputation nationwide as a highly skilled attorney and a tenacious trial lawyer in personal injury cases, business disputes, insurance claims, hurricane claims, and commercial litigation.